Dematerialisation of units and investments of AIFs and collection of stamp duty on units of AIFs
Chapter 11 - Dematerialisation of units and investments of AIFs and collection of stamp duty on units of AIFs
11.1. Issuance of units of AIFs in dematerialised form
Under Regulation 10(aa) of the AIF Regulations, AIFs shall issue their units in dematerialised form.
The issuance of units in dematerialised form shall be subject to the conditions specified by SEBI from time to time.
However, merely holding units in dematerialised form does not change the rules governing their transfer.
The terms governing transfer of dematerialised AIF units shall continue to be determined by:
The PPM.
Agreements entered into between the AIF and its investors.
Any other relevant fund documents.
11.2.1.
SEBI prescribed specific timelines and requirements for issuance and credit of AIF units in dematerialised form.
These requirements apply to AIFs/schemes of AIFs existing as on 11 December 2023.
The applicable timeline depends on the corpus of the scheme as on 31 October 2023 and whether investors have provided their demat account details.
11.2.1.
(a). Schemes with corpus ≥ ₹500 crore as on 31 October 2023
Units issued after 31 October 2023 shall be issued in demat form.
If the investor has provided demat account details, the units shall be credited directly to the investor's demat account.
If an investor was onboarded before 1 November 2023 but has not provided demat account details, the units shall be temporarily credited to the Aggregate Escrow Demat Account.
Example:
AIF Scheme A had a corpus of ₹600 crore as on 31 October 2023.
Investor A provides demat account details.
Units issued after 31 October 2023 shall be issued in demat form and credited directly to Investor A's demat account.
Investor B was onboarded before 1 November 2023 but has not provided demat account details.
Investor B's units shall be temporarily credited to the Aggregate Escrow Demat Account.
Once Investor B provides demat details, the units shall be credited to Investor B's demat account.
The required credit of demat units was to be completed by 31 January 2024.
(b). Schemes with corpus < ₹500 crore as on 31 October 2023 and schemes launched after 31 October 2023
Units issued after 30 April 2024 shall be issued in demat form.
If the investor has provided demat account details, the units shall be credited directly to the investor's demat account.
If an investor was onboarded before 1 May 2024 but has not provided demat account details, the units shall be temporarily credited to the Aggregate Escrow Demat Account.
Example:
AIF Scheme B had a corpus of ₹300 crore as on 31 October 2023.
Investor A provides demat account details.
Units issued after 30 April 2024 shall be issued in demat form and credited directly to Investor A's demat account.
Investor B was onboarded before 1 May 2024 but has not provided demat account details.
Investor B's units shall be temporarily credited to the Aggregate Escrow Demat Account.
Once Investor B provides demat details, the units shall be credited to Investor B's demat account.
The required credit of demat units was to be completed by 10 May 2024.
11.2.2.
Where investors have not provided their demat account details to the AIF within the prescribed timeline:
The AIF must follow the specified process for dematerialising and crediting the units already issued.
The prescribed process is intended to ensure that such investors' units are appropriately dematerialised and credited once the required demat account details become available.
Example:
Investor A was required to provide demat account details within the prescribed timeline but failed to do so.
The AIF cannot simply leave the units without following the prescribed dematerialisation and credit process.
The AIF must follow the process specified under Para 11.2.2 for handling Investor A's units.
11.2.2.
(a)
Managers of AIFs shall continue to contact existing investors who have not provided their demat account details.
The purpose is to obtain the investors' demat account details and credit the units already issued to their respective demat accounts.
Depositories shall also assist in this process as advised by SEBI.
The AIF industry and the two depositories shall follow the implementation standards formulated by the SFA in consultation with SEBI.
These implementation standards shall specify the steps to be taken by AIF Managers and Depositories to contact investors and facilitate the conversion and credit of their units in demat form.
(b)
Units already issued to existing investors who have not provided their demat account details shall be credited to a separate demat account called the “Aggregate Escrow Demat Account”.
The AIF shall open this account specifically for the purpose of holding demat units on behalf of such investors.
The Aggregate Escrow Demat Account is therefore used as a temporary holding account until the relevant investors provide their demat account details.
New units that are required to be issued in demat form to such investors shall also be allotted to them and credited to the Aggregate Escrow Demat Account.
Example:
Investor A already holds units in an AIF but has not provided demat account details.
Investor A's existing units shall be credited to the AIF's Aggregate Escrow Demat Account.
Later, the AIF issues additional units to Investor A in demat form.
Since Investor A has still not provided demat details, the new units shall also be allotted to Investor A and credited to the Aggregate Escrow Demat Account.
(c)
When an investor provides their demat account details to the AIF, the AIF shall transfer the investor's units held in the Aggregate Escrow Demat Account to the investor's own demat account.
The transfer must be completed within 5 working days from the date on which the investor provides the demat account details.
No transfer of AIF units from or within the Aggregate Escrow Demat Account is permitted for any purpose other than transferring the units to the respective investor's demat account.
Example:
Investor A's units are held in the Aggregate Escrow Demat Account because Investor A had not provided demat details.
Investor A subsequently provides their demat account details to the AIF.
The AIF must transfer Investor A's units from the Aggregate Escrow Demat Account to Investor A's demat account within 5 working days.
The units cannot be transferred from the Aggregate Escrow Demat Account to any other person or for any other purpose.
(d).
Units of AIFs held in the Aggregate Escrow Demat Account may be redeemed.
The redemption proceeds shall be paid directly to the respective investor's bank account.
The entire redemption process must have a full audit trail.
This ensures that there is a clear record of:
The units redeemed.
The investor to whom the units belonged.
The redemption proceeds paid to that investor.
Example:
Investor A's AIF units are held in the Aggregate Escrow Demat Account because Investor A has not provided demat account details.
Investor A requests redemption of those units.
The units may be redeemed from the Aggregate Escrow Demat Account.
The redemption proceeds shall be transferred to Investor A's bank account.
Proper records must be maintained to establish the complete trail from redemption of units to payment of proceeds.
(e).
Managers of AIFs shall maintain investor-wise KYC details for units held in the Aggregate Escrow Demat Account.
The KYC details shall include:
Name of the investor.
PAN of the investor.
Bank account details of the investor.
The Manager must also maintain a complete audit trail of the transactions relating to such units.
These investor-wise details and transaction records shall be reported to the Depositories and Custodians on a monthly basis.
Example:
Investor A's units are held in the Aggregate Escrow Demat Account.
The AIF Manager must maintain:
Investor A's name.
PAN.
Bank account details.
Audit trail of transactions involving Investor A's units.
The Manager must report this information to the Depository and Custodian every month.
(f).
The AIF industry shall adopt implementation standards formulated jointly by the SFA and depositories, in consultation with SEBI.
These standards are intended to ensure compliance with the provisions of this Chapter.
The implementation standards shall, among other things, specify the formats for maintaining and reporting information relating to units held in the Aggregate Escrow Demat Account.
The standards shall cover:
Investor-wise holdings.
Investor-wise transactions.
Reporting of such information to Depositories and Custodians.
Example:
An AIF has units belonging to multiple investors lying in its Aggregate Escrow Demat Account.
The AIF Manager must maintain investor-wise records showing:
The units held by each investor.
Transactions relating to those units.
Other prescribed information.
The Manager must maintain and report this information using the formats prescribed under the implementation standards.
(g).
Managers of AIFs shall comply with the implementation standards formulated by the SFA in consultation with SEBI.
These implementation standards provide the practical requirements that AIF Managers must follow for compliance with this Chapter.
The standards are published on the websites of:
Depositories.
Industry associations that are part of the SFA.
The relevant industry associations are:
Indian Venture and Alternate Capital Association (IVCA);
PEVC CFO Association; and
Trustee Association of India.
11.3. Reporting of value of units of AIFs to Depositories
The depository infrastructure is being leveraged to improve transparency and operational efficiency in the functioning of AIFs.
The framework also aims to ensure system readiness of:
AIFs.
Registrars and Transfer Agents (RTAs).
Depositories.
Accordingly, SEBI has specified certain requirements to facilitate the use of the depository system for AIF-related processes.
11.3.1.
AIFs, through their Registrars and Transfer Agents (RTAs), shall upload the latest available NAV for each ISIN of the AIF units in the depository system.
The NAV must be uploaded within 30 days from the date of valuation of the investment portfolio.
The requirement applies to each ISIN of units of the AIF.
11.3.2.
For the purpose of uploading the NAV within the prescribed 30-day period, the relevant valuation date shall be determined as follows:
(a). Independent Valuers
Where the valuation is carried out by independent valuers, the valuation date shall be the date of the valuation report.
Example:
Independent valuer issues the valuation report on 1 August 2026.
The valuation date will be 1 August 2026.
The 30-day period for uploading the NAV will be calculated from this date.
(b). Internal Valuers
Where the valuation is carried out by internal valuers, the valuation date shall be the date on which the valuation is documented in the internal records of the fund.
Example:
The internal valuer completes and documents the valuation in the fund's internal records on 5 August 2026.
The valuation date will be 5 August 2026.
The 30-day period for uploading the NAV will be calculated from this date.
11.3.3.
The Manager of the AIF shall be responsible for ensuring that the NAV is uploaded accurately and within the prescribed timeline.
The Manager must ensure that:
The correct NAV is uploaded.
The NAV is uploaded within the applicable 30-day period.
11.4. Directions to depositories
11.4.1.
The relevant authorities shall make the necessary amendments to their Bye-laws, Rules and Regulations to implement the provisions of this Chapter.
These amendments must also facilitate the creation and operation of the Aggregate Escrow Demat Account for AIFs.
The purpose is to ensure that the existing regulatory and operational framework supports the dematerialisation and holding of AIF units in the Aggregate Escrow Demat Account.
Example:
AIF units belonging to investors who have not provided demat account details need to be held in an Aggregate Escrow Demat Account.
The relevant Bye-laws, Rules and Regulations must therefore be amended, wherever necessary, to enable such an account to be created and operated for AIFs.
11.4.2.
A system shall be put in place to ensure that any transfer of AIF units held in dematerialised form is carried out in accordance with the applicable requirements.
Where the PPM, investor agreements or other fund documents require approval of the AIF or its Manager before a transfer, such approval must be obtained before the transfer is carried out.
Therefore, dematerialisation of the units does not remove any transfer restrictions or approval requirements contained in the fund documents.
Example:
Investor A holds AIF units in dematerialised form.
The PPM provides that any transfer of units requires prior approval of the AIF Manager.
Investor A wants to transfer the units to Investor B.
The transfer can be processed only after the AIF Manager gives the required approval.
The depository system must facilitate the transfer only after such approval is obtained.
11.4.3.
Necessary infrastructure shall be put in place to enable Registrars and Transfer Agents (RTAs) to upload the NAV of AIF units.
The infrastructure must also ensure that the uploaded NAV is properly reflected in the depository system.
This facilitates accurate and efficient availability of NAV information in the depository system.
Example:
An AIF's RTA calculates the latest NAV of its units.
The RTA uploads the NAV through the prescribed infrastructure.
The system ensures that the NAV is subsequently reflected in the relevant depository system.
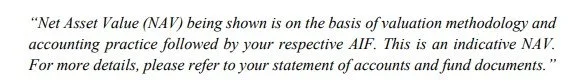
11.4.4. incorporate the following disclaimer wherever AIF NAV is being displayed:
The following disclaimer should be incorporated wherever AIF NAV is being displayed:
11.4.5.
The relevant entities shall inform their members/participants about the provisions of this Chapter.
They shall also publish and disseminate these provisions on their websites.
This ensures that members and participants are aware of the applicable requirements relating to the dematerialisation and depository framework for AIF units.
Example:
A depository has members/participants who are involved in the dematerialisation and transfer of AIF units.
The depository must:
Inform its members/participants about the provisions of this Chapter; and
Make the provisions available on its website.
11.5. Collection of stamp duty on issue, transfer and sale of units of AIFs
11.5.1.
The Government, through Gazette Notification S.O. 116(E) dated 8 January 2020, notified Registrars to:
An Issue and/or Share Transfer Agents (RTAs) registered under the SEBI RTA Regulations, 1993 as a “depository” for a limited purpose.
This recognition is specifically for acting as a “collecting agent” under the Indian Stamp Act, 1899 and the Rules made thereunder.
This applies only to instruments relating to transactions carried out:
Otherwise than through a recognised stock exchange; or
Otherwise than through a depository.
Therefore, an RTA is treated as a depository only for this specific stamp duty collection purpose, and not as a depository for all purposes.
11.5.2.
AIFs must comply with the applicable provisions of the Indian Stamp Act, 1899 and the Rules made thereunder.
The requirement relates to the collection of stamp duty on:
Sale of AIF units.
Transfer of AIF units.
Issue of AIF units.
This requirement applies with effect from 1 July 2020.
11.5.3.
The RTA appointed by an AIF shall be responsible for collecting stamp duty on:
Issue of AIF units;.
Transfer of AIF units.
Sale of AIF units.
The RTA must collect the stamp duty in accordance with the applicable provisions of the Indian Stamp Act, 1899 and the Rules made thereunder.
This requirement is in continuation of the framework specified under Para 11.5.1 and Para 11.5.2.
Example:
An AIF issues units to Investor A.
The RTA appointed by the AIF shall collect the applicable stamp duty on the issue of those units.
If Investor A subsequently transfers the AIF units to Investor B, the RTA shall collect the applicable stamp duty on the transfer in accordance with the Indian Stamp Act, 1899.
11.5.4.
Where AIF units are issued, transferred or sold in dematerialised form through a recognised Stock Exchange or Depository, the respective entity shall be responsible for collecting the applicable stamp duty.
The entities empowered to collect stamp duty are:
The recognised Stock Exchange;
The authorised Clearing Corporation; or
The Depository.
The collection of stamp duty shall be carried out in accordance with the amended Indian Stamp Act, 1899 and the Rules made thereunder.
This applies to transactions involving:
Issue of AIF units.
Transfer of AIF units.
Sale of AIF units.
Example:
An investor purchases AIF units in dematerialised form through a recognised Stock Exchange.
The applicable stamp duty shall be collected by the relevant Stock Exchange, authorised Clearing Corporation or Depository, as applicable.
Similarly, if AIF units are transferred through the Depository system, the Depository is empowered to collect the applicable stamp duty.
11.6. Holding investments of AIFs in dematerialised form
11.6.
Under Regulation 15(1)(i) of the AIF Regulations, AIFs are generally required to hold their investments in dematerialised form.
This requirement is subject to the conditions specified by SEBI from time to time.
However, the dematerialisation requirement does not apply to certain investments or schemes of AIFs that are specifically exempted by SEBI.
Therefore, the general rule is dematerialisation, subject to SEBI-specified exemptions.
Example:
An AIF makes an investment that falls within the investments covered by the dematerialisation requirement.
The AIF must hold that investment in dematerialised form, unless SEBI has specifically exempted that type of investment or scheme.
11.6.1.
Any investment made by an AIF on or after 1 July 2025 shall be held in dematerialised form only.
This requirement applies regardless of how the investment is acquired.
It applies where the AIF:
Makes the investment directly in the investee company.
Acquires the investment from another entity.
Example:
AIF A directly invests in the shares of Company X on 1 August 2025.
The shares must be held in dematerialised form.
AIF A purchases shares of Company Y from another investor on 1 September 2025.
Even though the AIF acquired the investment from another entity, the shares must still be held in dematerialised form.
11.6.2.
Investments made by an AIF before 1 July 2025 are generally exempt from the requirement of being held in dematerialised form.
However, this exemption does not apply in the following cases:
(a). Investee company is required to facilitate dematerialisation
If the investee company is required under applicable law to facilitate dematerialisation of its securities, the AIF's investment must be held in dematerialised form.
Example:
AIF invested in Company X before 1 July 2025.
Applicable law requires Company X to facilitate dematerialisation of its securities.
The AIF cannot rely on the exemption and must hold the investment in dematerialised form.
(b). AIF exercises control over the investee company
The exemption also does not apply where the AIF, either:
On its own.
Along with other SEBI-registered intermediaries/entities that are required to hold investments in dematerialised form.
exercises control over the investee company.
For determining whether control exists, the meaning of “control” under Regulation 2(1)(f) of the AIF Regulations shall be used.
Example:
AIF A made an investment in Company X before 1 July 2025.
AIF A, either independently or together with other relevant SEBI-registered entities, exercises control over Company X.
The investment will not qualify for the exemption.
The investment must therefore be held in dematerialised form.
